
Before you make an offer, check whether the property itself fits the rules. For first-time buyers, government help for first home buyers VIC can ease some upfront pressure, but support depends on more than your first-home status. Property type, price limits, ownership history, residency conditions and application timing all matter, and not every scheme can be combined.
When you’re budgeting for a deposit, stamp duty and other purchase costs, it can be hard to know which support to investigate first. This 2026 guide explains the Victorian and Australian Government options, including the First Home Owner Grant, stamp duty relief, the 5% Deposit Scheme, Help to Buy and the First Home Super Saver Scheme. Use it to identify relevant checks, then confirm current rules and timing with a lender, conveyancer or government agency before relying on assistance.
Key Takeaways
- Compare state and federal support by the purchase cost it may help with, then check whether the schemes can be used together.
- The First Home Owner Grant is limited to eligible new homes. Check property and residency conditions before including it in your budget.
- Use this guide to identify which government help for first home buyers VIC may be worth checking against your circumstances and shortlisted property.
- Confirm eligibility and application timing with the relevant agency and a qualified professional before relying on assistance or committing to a purchase.
Government help for first home buyers in VIC: what support is available?
Government help for first home buyers VIC includes different types of support, each aimed at a different part of the purchase. A grant may contribute towards buying or building an eligible new home, a stamp duty concession may reduce the duty payable, and deposit support may help eligible buyers purchase with a smaller deposit. None is automatic: property type and value, previous ownership and occupancy can affect eligibility.
Start by separating the costs you need help with. If you’re considering a new home, check the grant rules. For an established or new home, look into stamp duty relief. If saving a deposit is the main challenge, check federal deposit and super schemes. This is a starting point, not an eligibility assessment.
For a broader perspective on the place of property in Australian life, see Home ownership in Australia. If you’re also weighing up how your work situation affects a home loan, this video offers an introduction:
Which Victorian first home buyer benefits should you check first?
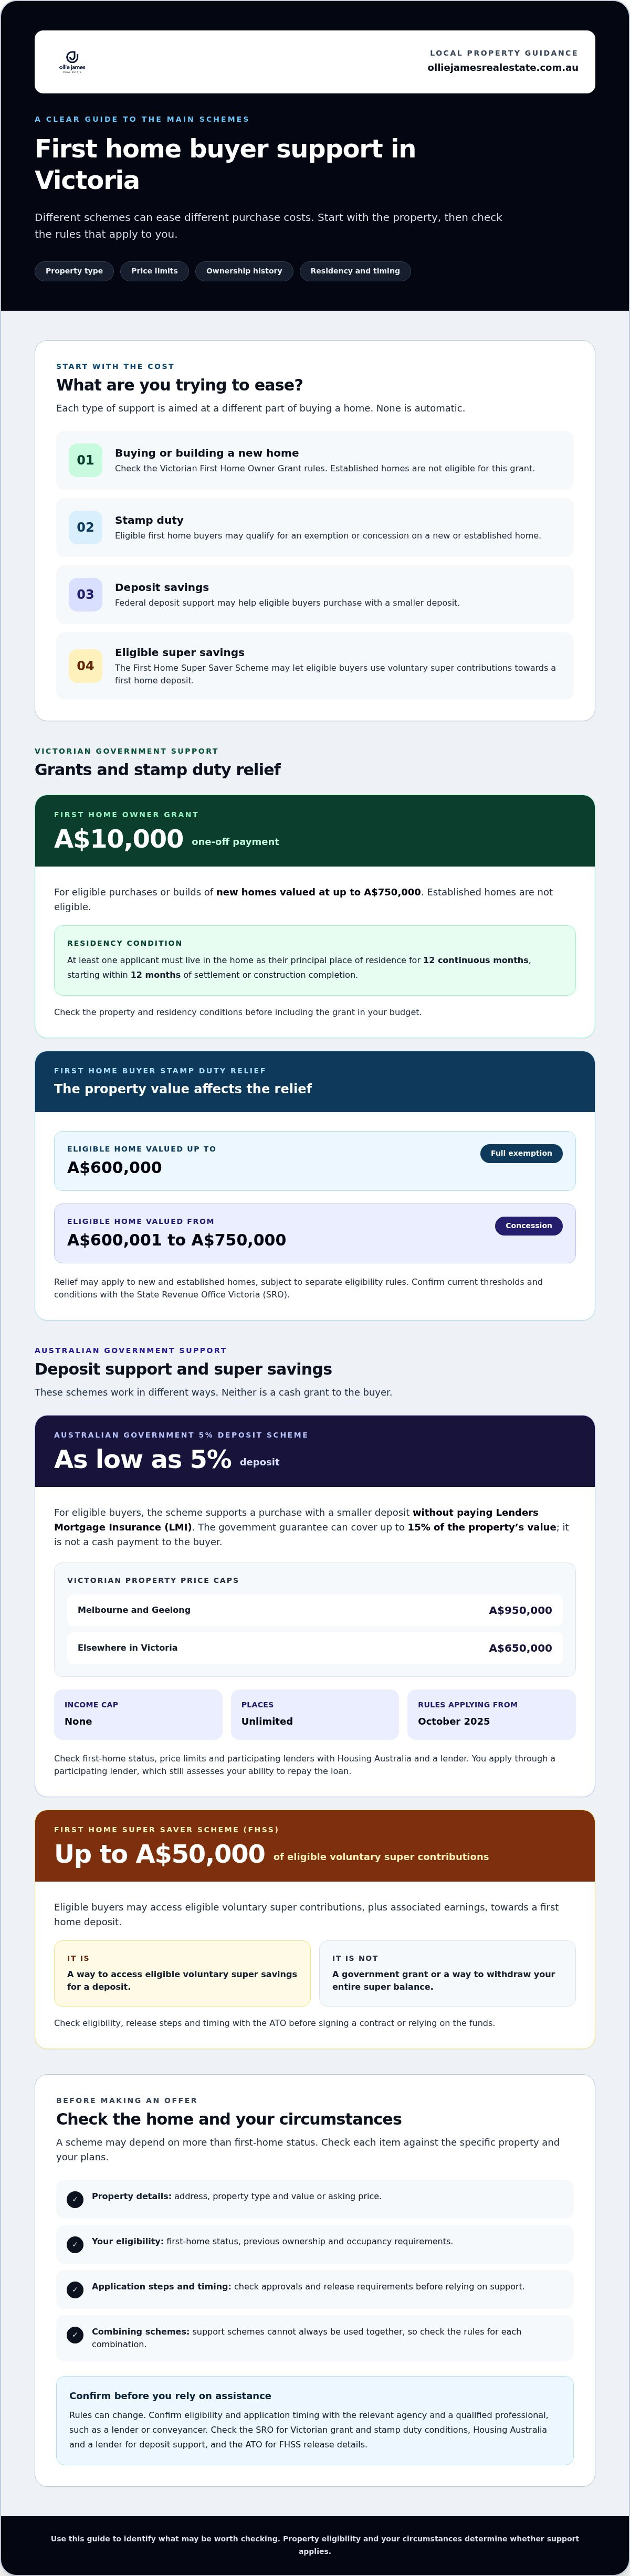
The Victorian First Home Owner Grant is a one-off A$10,000 payment for eligible purchases or builds of new homes valued at up to A$750,000. Established homes aren’t eligible. At least one applicant must live in the home as their principal place of residence for 12 continuous months, starting within 12 months of settlement or construction completion.
First home buyers may also qualify for a full stamp duty exemption on eligible homes valued up to A$600,000, or a concession when the value is A$600,001 to A$750,000. These apply to new and established homes, but separate eligibility rules apply. Check current thresholds and conditions with the State Revenue Office Victoria (SRO) before including either benefit in your budget.
Buying in Bendigo or nearby communities doesn’t automatically make a property eligible. Check the rules against the specific home, its value, your ownership history and your plans to live there. When comparing local properties, keep the address, property type and asking price together so you can check them against each scheme’s criteria. Local property guidance can help you assess homes, while the SRO and qualified professionals can clarify eligibility.
How federal deposit and super schemes may help Victorian first home buyers
Federal assistance may help with a deposit, but the schemes work in different ways. The Australian Government 5% Deposit Scheme, formerly the Home Guarantee Scheme, supports eligible buyers purchasing with a deposit as low as 5%, without paying Lenders Mortgage Insurance (LMI). The government guarantee can cover up to 15% of the property’s value. It isn’t a cash payment to the buyer.
How do the 5% Deposit Scheme and First Home Super Saver Scheme differ?
For the 5% Deposit Scheme, check first-home status, property price limits and participating lenders with Housing Australia and a lender. In Victoria, the price cap is A$950,000 in Melbourne and Geelong, and A$650,000 elsewhere. There’s no income cap and places are unlimited under the rules applying from October 2025. You apply through a participating lender, which still assesses your ability to repay the loan.
The First Home Super Saver Scheme (FHSS) lets eligible buyers access up to A$50,000 of eligible voluntary super contributions, plus associated earnings, towards a first home deposit. It isn’t a government grant or a way to withdraw your entire super balance. Check eligibility, release steps and timing with the ATO before signing a contract or relying on the funds.
Deposit support helps eligible buyers borrow with a smaller deposit, while the FHSS releases eligible voluntary super savings. Neither is a cash grant. These options have separate rules, and support schemes can’t always be combined. Confirm your circumstances with the scheme administrator and lender. For state assistance, check the SRO’s First Home Owner Grant guidance. If you’re starting to explore Bendigo homes, you can also browse local property options while confirming eligibility with the relevant agencies.
Check your eligibility and plan your first home purchase in Victoria
Scheme rules can change, so work through the checks in order rather than assuming support will apply. Before making an offer, compare the property’s details with each scheme’s criteria and make a separate note of any application or approval steps. This can help you identify gaps in your budget before you commit.
What should you confirm before making an offer?
- Confirm your first-home status. Check how each scheme treats previous property ownership, including ownership with another person.
- Shortlist a suitable property. Note its location, property type and price, then check those details against each scheme’s current criteria.
- Verify the rules with the right agency. Use the Victorian Government first home buyer support information and confirm state benefits with the State Revenue Office Victoria. For federal schemes, check Housing Australia or the Australian Taxation Office, as relevant.
- Talk through finance and timing. Ask a lender or mortgage broker about borrowing capacity, deposit requirements and whether a scheme suits your circumstances. Check when applications, approvals and any funds must be in place.
Processes and timing vary between schemes. Verify the latest requirements before signing a contract or counting on assistance, and ask a conveyancer about contract and settlement dates if you’re unsure. A Bendigo homes buying guide can help you frame your local search around your budget. To compare options across Bendigo, Kangaroo Flat, Junortoun, Epsom, Eaglehawk, Strathfieldsaye, Strathdale, Kennington, Golden Square, California Gully, Maiden Gully and Marong, explore Ollie James Real Estate’s local property listings. Government scheme eligibility should always be confirmed with the relevant agency or a qualified professional.
Take your next step with a clearer plan
Government help for first home buyers VIC can take different forms, from grants and stamp duty relief to deposit or superannuation support. The right option depends on your circumstances and the property you choose. Check eligibility, current thresholds and application timing directly with the relevant agency before relying on assistance.
Once you’ve confirmed what may apply, compare suitable homes with your budget and borrowing plans in mind. A lender, conveyancer or government agency can help clarify finance, scheme requirements and purchase timing. Keep a record of the property details and advice you receive so you can revisit the checks if you change your shortlist.
For local property guidance as you explore Bendigo and Central Victoria, Ollie James Real Estate is an independent, family-owned agency with over 17 years of local industry experience. Explore local property listings with Ollie James Real Estate and get in touch to discuss your search.
Frequently Asked Questions
Is the First Home Owner Grant available for established homes in Victoria?
Generally, no. Victoria’s First Home Owner Grant relates to eligible new homes, not established properties. Before assuming a home qualifies, confirm its property type and value, your occupancy plans and applicant circumstances with the State Revenue Office Victoria (SRO). These details can affect eligibility, so check current SRO guidance before signing or relying on the grant.
Can I use the Victorian first home buyer duty concession with a federal deposit scheme?
Potentially, yes. Victorian duty relief and a federal deposit scheme address different parts of a purchase, so one doesn’t automatically rule out the other. When comparing government help for first home buyers VIC, remember each scheme has separate eligibility criteria, property limits and processes. Whether they can work together depends on current rules and your circumstances, so confirm with the SRO and a participating lender.
How much deposit do first home buyers need in Victoria?
There isn’t one deposit amount for every buyer. It depends on the lender, property and your financial position. Eligible buyers may be able to use the Australian Government 5% Deposit Scheme to purchase with a 5% deposit, subject to the scheme’s criteria and lender assessment. Whether you’re looking in Bendigo, Kangaroo Flat, Junortoun, Epsom, Eaglehawk, Strathfieldsaye, Strathdale, Kennington, Golden Square, California Gully, Maiden Gully or Marong, ask a participating lender what applies.
Can I use super to buy my first home in Victoria?
The First Home Super Saver Scheme lets eligible first home buyers access eligible voluntary super contributions towards a deposit. Current rules allow release of up to A$50,000 in eligible voluntary contributions, plus associated earnings, subject to requirements. It doesn’t let you withdraw your entire super balance. Check the Australian Taxation Office’s current release rules, limits and application steps before relying on funds for a purchase.


