
Can you sell your current home and buy the next on the same day without relying on everything going perfectly? If you’ve searched for “simultaneous settlement property Victoria”, you’re likely weighing up more than matching dates: sale proceeds need to be available, and both transactions must be ready to complete. That uncertainty is understandable, especially when a delay could affect your move.
A same-day settlement can work, but it depends on timing, funding and a practical fallback. This guide explains the basic sequence, what needs to align and how it compares with bridging finance. You’ll also find questions to ask your lender and conveyancer, and ways your real estate agent can help keep sale communication and timing clear if dates or funds don’t line up.
Key Takeaways
- A simultaneous settlement links the sale of your current home with the purchase of your next, so confirm how funds are expected to flow with your lender and conveyancer.
- For a simultaneous settlement property Victoria plan, align contract dates early and ask each professional what needs to be ready before settlement day.
- Compare same-day settlement with bridging finance by considering how much you rely on sale proceeds, whether finance is confirmed and what could happen if a settlement is delayed.
- Agree on a fallback with your lender and conveyancer, and ask your selling and buying agents to keep timing and communication clear.
What does simultaneous settlement mean when buying and selling property in Victoria?
Buying your next home before the sale of your current one is complete can make the timing feel uncertain. A simultaneous settlement property Victoria arrangement coordinates both transactions to settle on the same day, with the sale proceeds intended to help fund the purchase. The exact sequence depends on your contracts, lender processes and settlement arrangements.
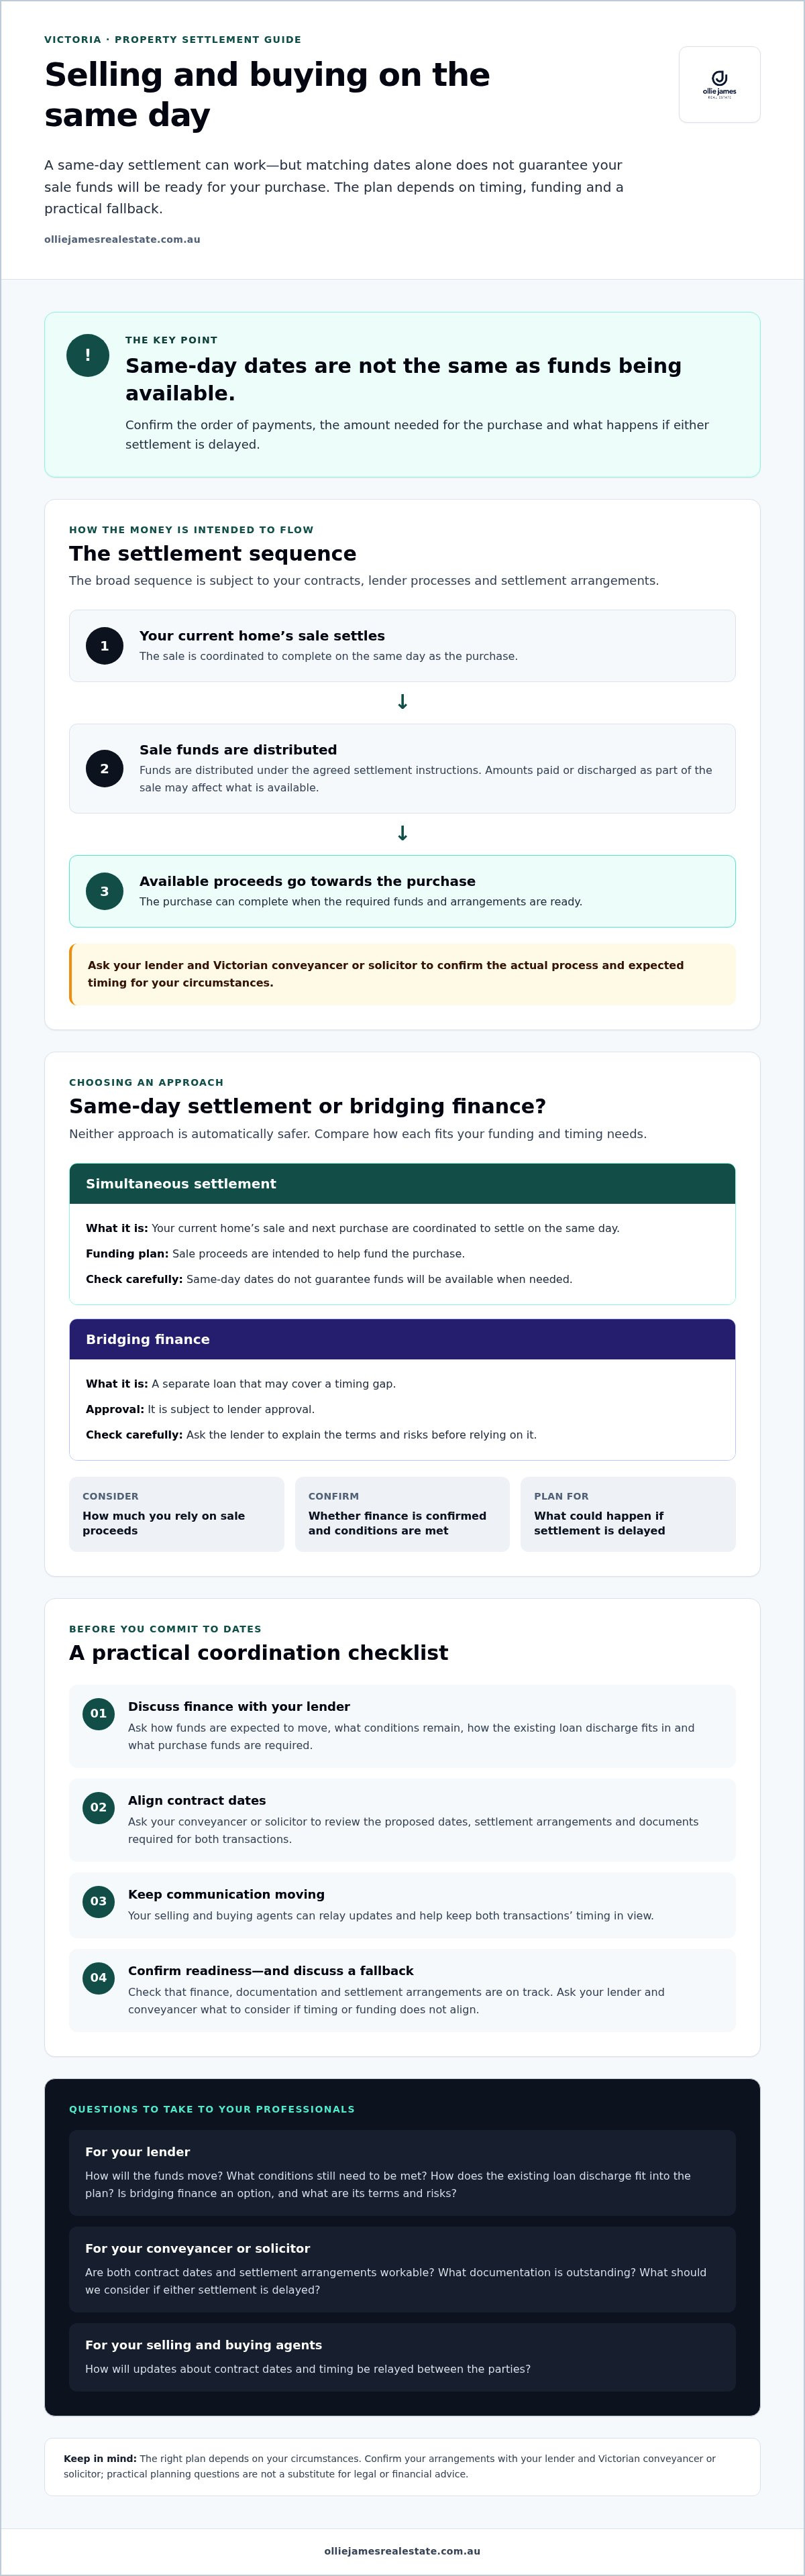
In broad terms, your existing home’s sale settles first, funds are distributed according to the settlement instructions, and the available proceeds are then used towards completing your purchase. The transactions may be coordinated electronically, but same-day dates alone don’t guarantee that funds will be available when needed. Ask your lender and Victorian conveyancer or solicitor to confirm the process for your circumstances. For background, conveyancing is the process involved in transferring property ownership.
For a closer look at the process, watch this video about what happens on settlement day:
How do the sale proceeds connect to the next purchase?
The broad sequence is sale settlement, distribution of funds under the agreed instructions, then purchase settlement. The amount available for your next home may depend on amounts that need to be paid or discharged as part of the sale. Ask your lender and conveyancer or solicitor to explain the steps, check the funds required and confirm the expected timing. Your selling and buying agents can help keep contract-date communication moving.
A simultaneous settlement coordinates a sale and purchase for the same day. Bridging finance is a separate loan that may cover a timing gap, subject to lender approval. If your sale proceeds may not be available in time, ask your lender whether bridging finance is an option, and confirm its terms and risks. The right plan depends on your circumstances, not simply the settlement dates.
Simultaneous settlement property Victoria: how to plan the timing
Good coordination starts before you commit to settlement dates. A simultaneous settlement property Victoria plan involves several parties, and same-day dates don’t remove the risk of a delay, a funding condition or sale proceeds being unavailable when expected. Set out the steps with your lender and conveyancer or solicitor, then keep both agents informed as dates and requirements are confirmed.
- Discuss finance: Ask your lender what needs to happen for your sale proceeds, existing loan discharge and purchase funds. Confirm what conditions still need to be met.
- Align contract dates: Have your conveyancer or solicitor review the proposed dates and explain the settlement arrangements and documents required.
- Coordinate communication: Your selling and buying agents can relay updates and help keep both transactions’ timing in view.
- Confirm readiness: Check with the relevant professionals that finance, documentation and settlement arrangements are on track. Discuss what to do if either settlement is delayed.
What should you confirm with your lender and conveyancer?
Ask your lender how funds are expected to move, what conditions must be met and how the existing loan discharge fits into the plan. Ask your conveyancer or solicitor to confirm both contract dates, the settlement arrangements and any outstanding documentation. These are practical questions, not a substitute for legal or financial advice. Consumer Affairs Victoria’s Buying and selling property in Victoria information is a useful state-specific reference. PEXA is an Australian electronic conveyancing entity; ask your conveyancer whether and how it applies to your transactions.
Discuss a fallback before the dates approach. Ask your lender and conveyancer what options to consider if the timing or funding doesn’t align, rather than assuming a same-day plan will proceed as scheduled. If you’re preparing to sell in Bendigo or Central Victoria, you can learn about local residential sales support as an early planning step.
Simultaneous settlement or bridging finance: choose a plan with a fallback
Neither approach is automatically safer. With a simultaneous settlement property Victoria arrangement, you’re relying on the sale and purchase completing in coordination, with sale proceeds intended to contribute to the next purchase. Bridging finance may help cover a gap if you buy before your existing home sells, but it depends on lender approval and the lender’s terms. Compare how much you rely on sale proceeds, whether finance is confirmed and how you would manage a delay before choosing.
Ask your lender to explain eligibility, repayment arrangements, costs and risks for any bridging option. For a same-day plan, ask your lender and conveyancer or solicitor what happens if funds or settlement readiness don’t align. An agent can help coordinate sale communication and discuss local timing, but can’t confirm finance or legal requirements.
What happens if one settlement is delayed?
The consequences depend on the contracts, finance arrangements and circumstances. Don’t assume one transaction will automatically move with the other, or that a delay will have a particular legal or financial outcome. Before committing to dates, ask your conveyancer or solicitor and lender which contingency options may be available and what steps you’d need to take if either settlement changes.
Use this checklist to shape those conversations:
- Confirm proposed dates and key dependencies with your lender and conveyancer or solicitor.
- Check how the sale proceeds, loan discharge and purchase funds are expected to be handled.
- Agree who will update each party if dates or readiness change.
- Discuss a fallback for a delay, including whether lender-approved bridging finance is an option.
If you’re selling in Bendigo, the Bendigo home-selling guide offers related sale-planning advice. For a clearer picture of local sale timing, discuss your plans with a local real estate agent before settling on dates.
Plan your next move with greater confidence
A simultaneous settlement can help connect your sale and purchase, but success depends on more than matching dates. Confirm how funds will flow, check finance and contract requirements with your lender and conveyancer, and agree on a fallback if timing changes. Comparing this with bridging finance can help you choose a plan that fits your circumstances.
If you’re considering a simultaneous settlement property Victoria plan, a clear picture of your home’s likely sale value can help you plan the next step. Ollie James Real Estate is an independent, family-owned agency supporting residential sales across Bendigo and Central Victoria, with more than 17 years of local industry experience. The team works with sellers across Bendigo, Kangaroo Flat, Junortoun, Epsom, Eaglehawk, Strathfieldsaye, Strathdale, Kennington, Golden Square, California Gully, Maiden Gully and Marong. You can request a free, no-obligation property appraisal as an early planning step.
Frequently Asked Questions
What is a simultaneous settlement when buying and selling property?
A simultaneous settlement is a coordinated sale and purchase that complete on the same day. Typically, sale proceeds are intended to contribute to the next purchase, subject to the lender’s arrangements and settlement instructions. It isn’t the same as bridging finance, which is a separate loan that may cover a timing gap if a lender approves it.
Can you have a simultaneous settlement in Victoria?
Yes, a simultaneous settlement can be arranged in Victoria when the sale, purchase and funding are coordinated. A simultaneous settlement property Victoria plan needs your lender and conveyancer or solicitor to confirm the dates, funds and requirements. Same-day timing doesn’t guarantee completion. If selling in Bendigo, Kangaroo Flat, Junortoun, Epsom, Eaglehawk, Strathfieldsaye, Strathdale, Kennington, Golden Square, California Gully, Maiden Gully or Marong, discuss likely sale timing with your agent early.
Is bridging finance better than a simultaneous settlement?
Neither option is universally better. A same-day settlement relies on the sale and purchase being ready together, with sale funds available as planned. Bridging finance may offer flexibility if you buy before selling, but approval, eligibility, terms and risks depend on the lender and your circumstances. Ask your lender to compare the options against your expected dates and financial position.
What happens if one property settlement is delayed?
If one settlement is delayed, the effect on the linked transaction depends on the contracts, funding arrangements and cause of the delay. Don’t assume the other settlement will automatically move or that a particular outcome will follow. Contact your conveyancer or solicitor and lender promptly, and ask about contingency options before committing to dates.
Planning a sale in Bendigo or Central Victoria? Request a free, no-obligation property appraisal from Ollie James Real Estate to help inform your next move.


