
A 20% deposit isn’t the only path to buying your first home in Bendigo: eligible buyers using the Regional First Home Buyer Guarantee can buy with a 5% deposit and borrow up to 95% of the property’s value without lenders mortgage insurance. Bendigo is within regional Victoria, but the home and buyer must meet the scheme’s eligibility rules.
It’s understandable to feel that saving a deposit is the biggest hurdle, especially when grant rules and other buying costs add to the decisions. This guide explains how the regional guarantee works, what lenders mortgage insurance means and how your deposit affects your loan. It also covers Victorian support: according to the State Revenue Office Victoria, eligible first-home buyers purchasing or building a new home valued up to A$750,000 may qualify for the First Home Owner Grant. The grant is separate from the guarantee, so understanding how each may apply can help you plan your next steps with greater confidence.
Key Takeaways
- Set a savings target that accounts for your deposit, loan repayments and other purchase costs, including whether lenders mortgage insurance may apply.
- Before relying on the Regional First Home Buyer Guarantee, assess its eligibility rules, including regional residency, owner-occupier requirements and income and property limits.
- Consider the First Home Owner Grant separately from stamp duty concessions, and understand how new-home eligibility may affect your purchase plans.
- Compare Bendigo locations, home styles and prices to focus your search on properties that suit your budget and needs.
Deposit requirements and lenders mortgage insurance
In Australia, a 20% deposit is commonly needed to avoid lenders mortgage insurance (LMI). Eligible buyers may use the Australian Government 5% Deposit Scheme to buy with a smaller deposit and no LMI.
Saving for a deposit
Start with a household budget that tracks income and expenses. This shows how much you can regularly save and where spending changes may help. Credit card, car and personal loan repayments reduce the money available for a deposit, so include them in your calculations. A larger deposit means borrowing less and may reduce repayments.
Estimating deposit and purchase costs
Budget for more than the deposit. Potential purchase costs include loan application and legal fees, stamp duty, home and contents insurance, and LMI if it applies. These costs affect how much savings you’ll have left after settlement, so include them in your overall target. Stamp duty and other costs depend on the purchase and your circumstances.
Meeting deposit requirements
A typical Australian home deposit is 5-20% of the property price. Buyers usually need 20% to avoid LMI, while a smaller deposit may mean paying this insurance. LMI protects the lender, not the borrower. Compare the cost of a smaller deposit and LMI with the time needed to save more, and consider how each option affects your loan and repayments.
Using the 5% Deposit Scheme
Under the Australian Government 5% Deposit Scheme, eligible buyers can purchase with a minimum 5% deposit without LMI. Applicants must be at least 18, Australian citizens or permanent residents, and hold a Medicare card. They must intend to live in the home, demonstrate an ability to save over time, and meet the property and ownership rules. Eligibility may include not having owned property in Australia in the last 10 years. The scheme has no income caps or waitlists.
What is the regional First Home Buyer Guanentee?
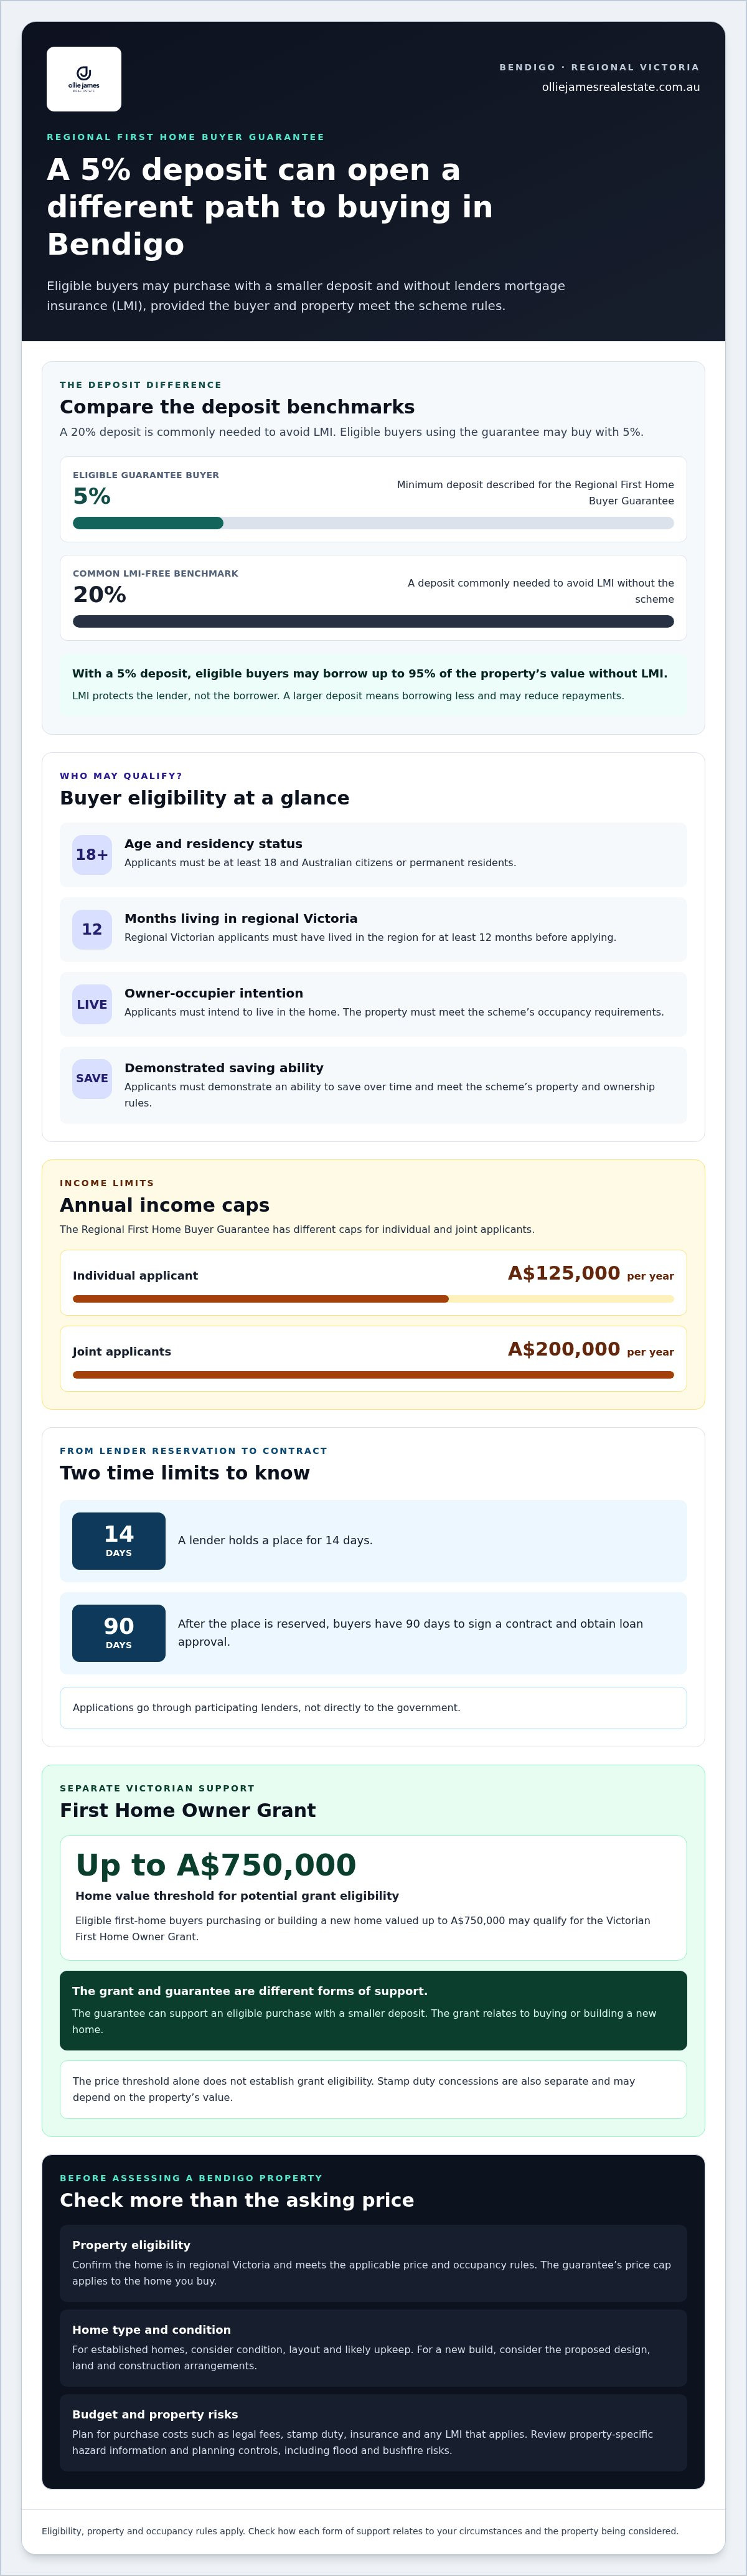
The Regional First Home Buyer Guarantee can help eligible buyers purchase a Bendigo home with a 5% deposit, borrowing up to 95% of its value without lenders mortgage insurance. The home must be in regional Victoria and meet the scheme’s price and occupancy rules.
Applicants must be at least 18 and Australian citizens or permanent residents. In regional Victoria, they must have lived in the region for at least 12 months before applying. The individual income cap is A$125,000 per year, or A$200,000 per year for joint applicants. Check that the property meets the applicable eligibility and occupancy requirements before proceeding. Applications go through participating lenders, not directly to the government. A lender holds a place for 14 days; after it’s reserved, buyers have 90 days to sign a contract and obtain loan approval.
For established homes, compare the property’s condition, layout and likely upkeep with your needs. A new build involves different decisions, so consider the proposed design, land and construction arrangements before committing. The Regional First Home Buyer Guarantee’s price cap applies to the home you buy.
Compare locations, home styles and asking prices with your budget before narrowing your search. Median house and unit prices vary by property type and reporting period, so use a dated local snapshot and compare like with like.
For flood, bushfire and planning risks, review property-specific hazard information and planning controls. Consider how these could affect the site and your intended use. These checks help you assess a property beyond its asking price.
Victorian First Home Owner Grant eligibility
In Victoria, eligible first home buyers purchasing or building a new home valued up to A$750,000 may qualify for the First Home Owner Grant, according to sro.vic.gov.au. The price threshold is important, but it doesn’t alone establish eligibility. The grant is specifically relevant to a new home, so buyers considering established Bendigo properties should factor that difference into their plans.
Keep the Victorian First Home Owner Grant separate from the Regional First Home Buyer Guarantee. The guarantee can support an eligible purchase with a smaller deposit, while the Victorian grant relates to buying or building a new home. Victorian first home buyers may also receive a partial or full stamp duty exemption depending on the property’s value. These are separate forms of support, so don’t assume one automatically includes the others.
To buy your first home in Victoria, start by setting a budget and identifying suitable locations and property types. Compare the home’s price and whether it’s new or established with the relevant support criteria. Arrange finance, review the contract and plan for settlement costs before committing. For a new build, include both the land and proposed home in your affordability planning.
Bendigo’s regional setting may appeal if you’re weighing options beyond Melbourne and other cities. Compare homes against your needs, not just a grant threshold: location, layout and ongoing costs all affect whether a property suits you. A grant can inform your budget, but it shouldn’t be the only reason to choose a home.
Ready to compare local homes with your plans? Explore residential property options as you narrow your search.
Ollie James Real Estate: Residential Property Sales
Ollie James Real Estate helps buyers compare homes and plan a purchase through its Residential Sale service in Bendigo. Once you’ve considered your deposit, finance and relevant grants, explore properties that suit your needs and budget.
Whether you’re considering an established home or a block of land, local property options can help you assess location, layout and suitability before deciding. Ollie James Real Estate also sells vacant land, giving you another option to consider when weighing where and what to buy. Compare each property with your priorities rather than relying on grant eligibility alone.
For a practical next step in your Bendigo property search, contact Ollie James Real Estate to discuss buying a home or land.
Make your next move with confidence
A clear plan can make buying your first home in Bendigo feel more manageable. When deciding what to view, focus on the features and location that suit your everyday life, then take the next step at a considered pace.
Ollie James Real Estate offers residential sales and vacant land sales for people exploring homes or land across the region. If your plans change and you decide to rent out a property, its property management service may also be relevant. The right next step depends on what you want to buy and how you plan to use it.
If you’re ready to explore local property options, contact Ollie James Real Estate to start a conversation. You can move forward with a clearer sense of what matters to you and the kind of home that could feel right.
Frequently Asked Questions
Why Choose Bendigo for Your Next Home?
Bendigo offers regional living with road and rail connections to Melbourne in just under two hours. Its gold rush heritage is visible at the Central Deborah Gold Mine and on historic trams, while the Bendigo Easter Festival and other arts and music events add to the city’s calendar. Explore neighbourhoods such as Kangaroo Flat, Junortoun, Epsom, Eaglehawk, Strathfieldsaye, Strathdale, Kennington, Golden Square, California Gully, Maiden Gully and Marong.
What are the eligibility rules for the Victorian First Home Owner Grant?
Eligible first home buyers purchasing or building a new home valued up to A$750,000 may qualify for the Victorian First Home Owner Grant, according to sro.vic.gov.au. The new-home condition matters: an established property doesn’t meet the purchase description in this grant rule. If you’re comparing new and established homes, include eligibility alongside the property’s price and your broader purchase budget.
How much deposit do you need to buy a first home in Bendigo?
A 20% deposit is commonly needed to avoid lenders mortgage insurance, while eligible buyers may use the Australian Government 5% Deposit Scheme with a minimum 5% deposit. The deposit is calculated against the property’s value, so your target changes with the home price. Keep purchase costs separate in your savings plan, since the deposit won’t cover every expense connected with buying.


